Introduction
Banks increasingly use social media to promote products, educate customers, answer questions, build trust, and support community engagement. However, banking communications operate within a regulated environment. A social post can involve advertising, consumer protection, privacy, records retention, employee activity, or customer complaints.
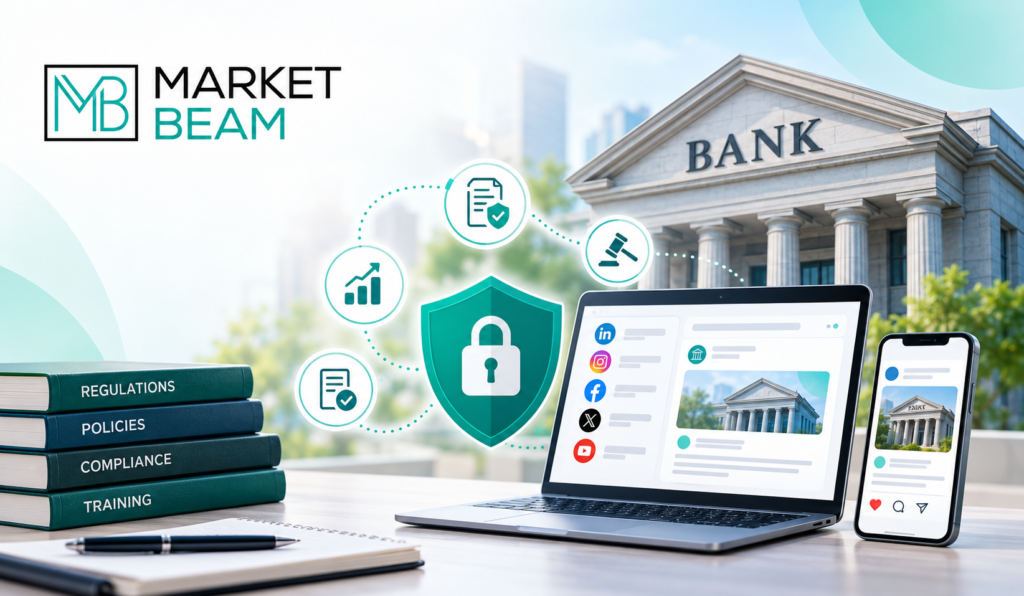
That makes banking social media compliance an important part of a bank’s broader compliance management program. The Federal Financial Institutions Examination Council (FFIEC) guidance explains that existing consumer protection and compliance laws apply to financial institution activities conducted through social media. It also recommends risk management covering governance, policies, employee training, monitoring, third-party relationships, and audit functions.
For modern banks, the challenge is not simply creating a social media policy. Teams also need a practical process for creating, reviewing, approving, publishing, monitoring, and retaining social communications.
What Is Banking Social Media Compliance?
Banking social media compliance is the process of managing a bank’s social media communications in accordance with applicable laws, regulations, supervisory expectations, and internal policies.
The FFIEC guidance specifically covers banks, savings associations, credit unions, and certain nonbank entities supervised by the CFPB. It notes that social media may be used for advertising, marketing, account applications, customer interaction, feedback, complaints, and other activities.
Importantly, the guidance does not create a separate set of social media laws. Instead, it explains that existing consumer protection and compliance requirements continue to apply when financial institutions use social media.
Therefore, banking social media compliance should be integrated into the bank’s existing compliance and risk management framework.
Why Banking Social Media Compliance Matters
Social media is fast, public, and highly interactive. A bank may publish a promotion in the morning and receive hundreds of comments by the afternoon.
That creates several risks. A customer could ask about a loan rate in a public comment. An employee could accidentally make an unsupported statement. A marketing post could include information that requires additional disclosures. A fraudulent account could impersonate the bank.
The FFIEC guidance identifies compliance and legal risks, operational risks, and other social media-related risks and recommends controls proportionate to the institution’s activities.
For this reason, banking social media compliance needs to cover both planned content and ongoing interactions.
Key Areas of Banking Social Media Compliance
1. Bank Social Media Policy
A clear bank social media policy is the foundation of banking social media compliance.
The policy should explain who can manage official accounts, who can create and approve content, what employees can post, how customer interactions should be handled, and when issues must be escalated.
The FFIEC guidance recommends policies and procedures covering the use and monitoring of social media, applicable compliance requirements, online postings, edits, replies, and retention.
Policies should also be reviewed regularly because social platforms, products, and regulatory expectations can change.
2. Financial Promotions
Banks frequently use social media to advertise checking accounts, savings products, credit cards, mortgages, loans, and other services.
The FFIEC notes that when social media is used to market products or originate accounts, financial institutions should address applicable consumer protection and compliance requirements. For example, Regulation DD can require specific information when an electronic advertisement uses certain triggering terms related to deposit accounts.
This makes banking social media compliance especially important for promotional campaigns.
Marketing teams should work with compliance teams to review product claims, rates, offers, eligibility language, and applicable disclosures before publication.
3. Data Privacy
Data privacy is another major part of banking social media compliance.
The FFIEC guidance notes that privacy requirements can become relevant when financial institutions collect or access information about consumers through social media. It specifically discusses the relevance of the Gramm-Leach-Bliley Act (GLBA) privacy and security requirements in certain social media activities.
Banks should therefore avoid requesting sensitive account information through public comments or unsecured social interactions.
Customer service teams should provide clear guidance on when conversations must move to secure channels. Employees should never ask customers to post account numbers, passwords, authentication information, or other sensitive data publicly.
Employee Social Media and Producer-Like Risks
Employees can create another layer of risk.
A bank employee may use an official account, a professional profile, or another social channel to communicate about the organization. Without clear controls, employees may accidentally publish unauthorized claims or disclose information that should remain private.
The FFIEC guidance recommends employee training as part of a social media risk management program and recommends defining impermissible activities where appropriate.
A practical banking social media compliance program should therefore combine policy with recurring training.
Training should cover approved messaging, customer interactions, confidential information, escalation procedures, personal versus business communications, and the use of official social accounts.
Records Retention
Records retention should be built into banking social media compliance from the beginning.
Social communications may need to be retained according to applicable laws, regulations, and the bank’s records management policies. FFIEC guidance specifically recommends addressing retention of social media postings, edits, and replies.
The exact retention requirement can depend on the communication and the applicable rule. Banks should therefore establish retention schedules with their compliance and records management teams.
A useful system should make it possible to identify the final published communication, approval history, author, account, publication date, and relevant revisions.
Monitoring and Customer Interactions
Strong banking social media compliance continues after publication.
Banks should monitor official social channels for customer complaints, misleading responses, potential fraud, impersonation, inappropriate employee activity, and other issues requiring escalation.
The FFIEC recommends oversight processes for monitoring information posted to proprietary social media sites administered by the financial institution or a third party. It also recommends audit and compliance functions for ongoing review.
Monitoring can also help banks identify fraudulent accounts and spoofing activity. The FFIEC specifically notes that financial institutions should consider social media monitoring tools and techniques to identify brand misuse, including phishing and spoofing.
Common Banking Social Media Compliance Risks
| Risk Area | Example | Recommended Control |
|---|---|---|
| Financial promotions | Unclear product or rate claims | Compliance review before publishing |
| Privacy | Customer shares account information publicly | Secure-channel response procedure |
| Employee activity | Unapproved financial statement | Training and approval controls |
| Recordkeeping | Missing final social post | Centralized archiving |
| Customer complaints | Sensitive complaint handled publicly | Escalation workflow |
| Impersonation | Fake account uses bank branding | Continuous monitoring |
| Third parties | Agency publishes without proper review | Vendor oversight |
These controls make banking social media compliance a repeatable process rather than an informal marketing responsibility.
Build a Banking Social Media Compliance Workflow
Banks can simplify banking social media compliance by creating a clear workflow:
Plan → Create → Review → Approve → Publish → Monitor → Archive
The first stage defines the campaign objective and audience. Marketing then creates the content using approved messaging.
Next, compliance or other designated reviewers evaluate the post. Higher-risk communications can receive additional review.
Once approved, authorized users publish the final version. Monitoring then begins, and required records are retained.
A centralized workflow also helps teams answer important questions: Who approved this post? Was the published version the approved version? When was it published? Which account published it?
Technology for Banking Social Media Compliance
Technology can make banking social media compliance easier to manage across large teams.
Instead of using separate email threads, spreadsheets, social publishing tools, and shared folders, banks can centralize content workflows, permissions, approvals, monitoring, and reporting.
MarketBeam provides social media compliance capabilities for regulated financial services organizations and describes features including regulatory prechecks, approval workflows, compliance-gated publishing, employee advocacy, monitoring, and audit trails.
The value of technology is not simply automation. It is visibility. Marketing teams can understand where content is in the workflow, while compliance teams can maintain better oversight.
Third-Party and Agency Oversight
Many banks use external agencies, technology providers, or other third parties to support social media programs.
The FFIEC guidance recommends risk management processes for selecting and managing third-party relationships associated with social media. It also makes clear that outsourcing a social media function does not remove the financial institution’s responsibility for appropriate oversight.
Therefore, banking social media compliance should extend to vendors and agency partners.
Contracts, access permissions, approval requirements, escalation procedures, and monitoring responsibilities should be clearly defined.
Best Practices for Banking Social Media Compliance
A practical banking social media compliance program should start with clear ownership.
Assign responsibilities across marketing, compliance, legal, information security, customer service, and executive management where appropriate.
Next, classify content based on risk. Routine corporate updates may follow a standard review, while financial promotions or customer-facing offers may require additional checks.
Use approved templates for frequently used campaigns. This can reduce unnecessary review work while keeping important messaging consistent.
Finally, measure the effectiveness of the program. The FFIEC guidance recommends reporting that allows senior management and the board to periodically evaluate the effectiveness of the social media program.
How MarketBeam Supports Banking Social Media Compliance
MarketBeam is designed to help regulated financial services organizations manage social media through structured workflows.
The platform describes social publishing, compliance automation, employee advocacy, monitoring, analytics, and audit-oriented capabilities for financial services organizations.
For banks, this approach can connect content creation, regulatory checks, approvals, publishing, employee activity, and monitoring in one workflow.
A centralized process can help marketing teams move faster while giving compliance stakeholders greater visibility into social activity.
Conclusion
Banking social media compliance is not simply a marketing checklist. It is part of a bank’s broader compliance and risk management program.
The FFIEC guidance makes clear that existing consumer protection and compliance requirements apply to financial institutions using social media, while also highlighting governance, policies, training, monitoring, third-party oversight, and audit functions.
The strongest approach combines a clear bank social media policy with controlled financial promotions, privacy safeguards, employee training, records retention, monitoring, and defined escalation procedures.
Technology can further support banking social media compliance by connecting approvals, publishing, monitoring, and documentation in a centralized workflow. MarketBeam provides compliance-focused social media management capabilities for regulated financial services teams.
Connect With Us
Looking for a more structured approach to banking social media compliance?
MarketBeam helps regulated financial services teams manage social content, approvals, publishing, monitoring, employee advocacy, and compliance workflows in one connected environment.
Sales
Tech Support
FAQs
1. What is banking social media compliance?
Banking social media compliance is the process of managing bank social media activity according to applicable regulations, consumer protection requirements, internal policies, privacy controls, and records management procedures.
2. Does banking regulation apply to social media?
Yes. FFIEC guidance explains that existing consumer protection and compliance laws apply to financial institution activities conducted through social media.
3. What should a bank social media policy include?
A bank social media policy should address account ownership, employee responsibilities, content standards, approvals, customer interactions, monitoring, escalation, privacy, third-party relationships, and records retention.
4. Why is records retention important?
Banks need processes for retaining applicable social media communications, including posts, edits, and replies, according to relevant requirements and internal records policies.
5. How should banks handle customer information on social media?
Banks should avoid requesting sensitive account information through public social channels and should provide clear procedures for moving customer conversations to secure communication methods.
6. How can technology improve banking social media compliance?
Technology can centralize content review, approvals, permissions, publishing, monitoring, analytics, and records. This can improve visibility and reduce manual compliance work.